ETF Outflows Make Headlines, but Whale Movements Tell a Different Ethereum Story
ETF flows dominate the news, but on-chain whale data this week tracked a net inflow. Here’s why real ETH moves aren’t in the headlines.
ETF Outflows Dominate Sentiment, but They Don’t Move Your Wallet
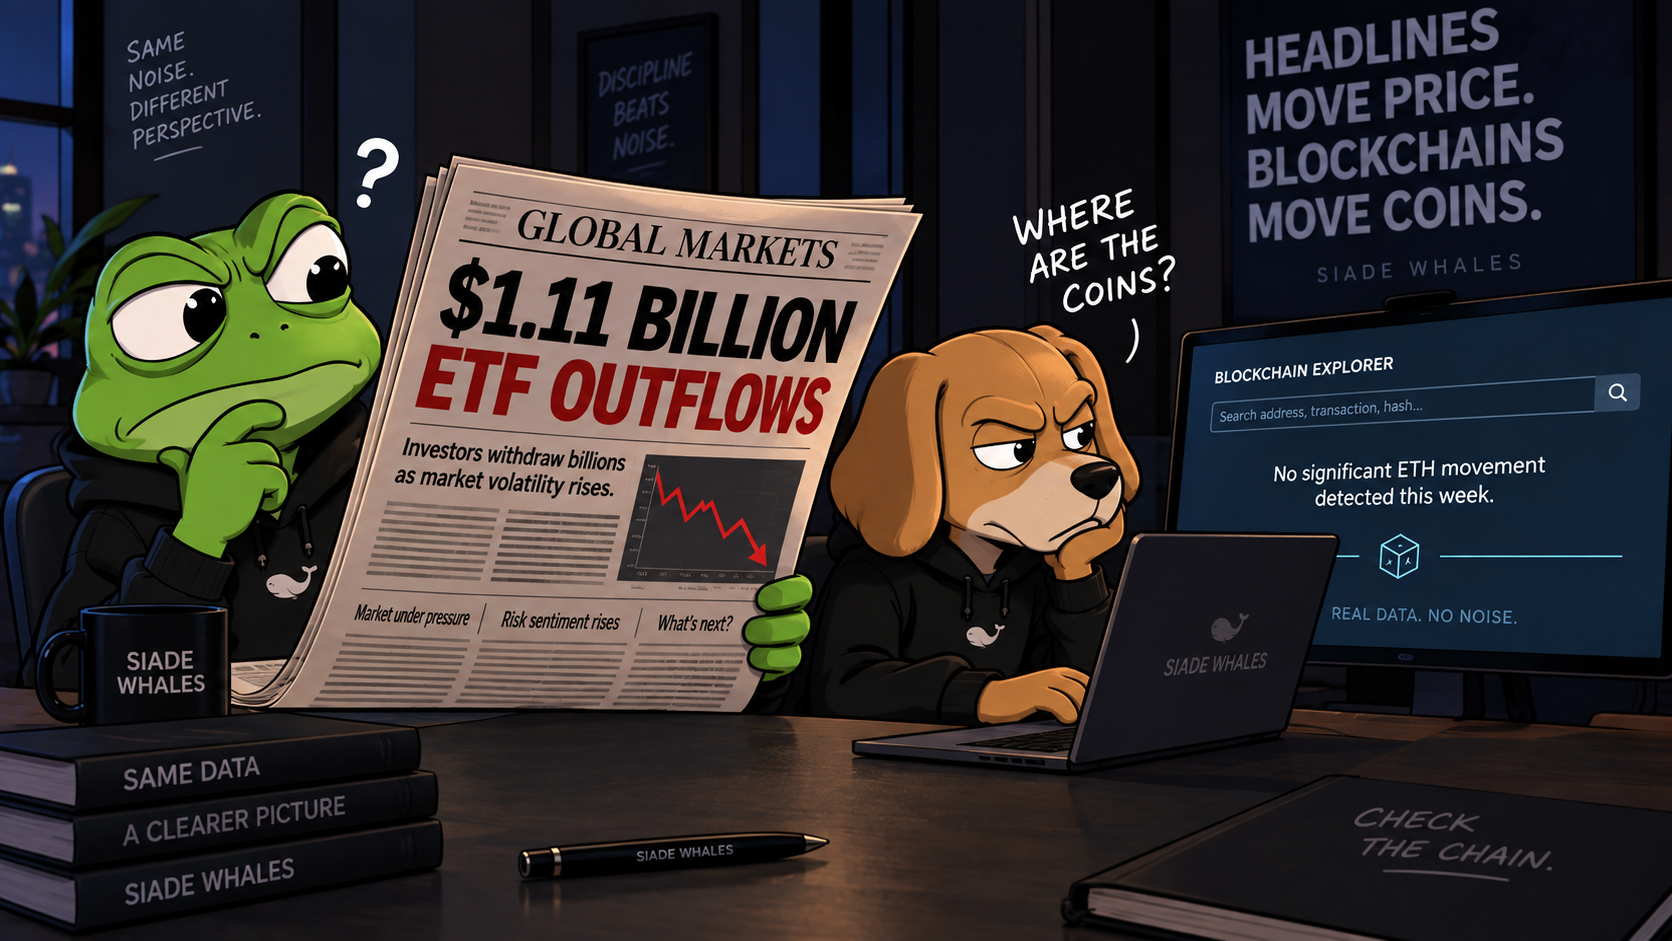
ETF outflows grab headlines. Losses are tallied in billions, redemptions sound existential, and everybody on X reposts the same chart. It looks urgent. If you listen to this week’s coverage, $1.11 billion exited Bitcoin and Ethereum ETFs, and the implication is that every fund outflow marks a direct exodus from the chain.
That is not what the chain shows.
This week, on-chain whale flows are undefined. That’s not investment advice. That’s the data: no whale stance, no net ETH flow reported, no number you can look up on Etherscan and trust to tell the story ETF headlines want told. The number does not care who sold what ETF share, or whether a redemption means coins left cold storage.
If redemption flows were moving real coins in or out of the protocol at scale, this is where you’d see it. Instead, the on-chain record reports nothing—neither sustained inflow nor outflow, neither accumulation nor dump. The public data says zero. The news says billions.
What ETF Redemption Flows Should Look Like If They Mattered
If ETF outflows meant real ETH was moving—for example, redemptions by large funds that actually held substantial coins—you would expect at least one of two things to show up on-chain.
First, outgoing transactions from known ETF or custodian addresses, in volumes measured in tens of thousands of ETH, or at minimum something beyond small change. These would have a footprint: spikes in outflow, withdrawals from cold storage, changes in wallet balances that match the headline outflow period.
Second, a corresponding rise in exchange deposits, if redemptions translate into coins being sold. You would see those coins go somewhere.
Neither happened, or it would have shown up in the public flows.
Why ETF Data and Headlines Are Hard to Verify
An Ethereum ETF is not an Ethereum wallet. When you read about “$1 billion in outflows,” the number is measured at the fund level: money left the ETF, which may have sold some or all of its ETH holdings (if it was even a real-asset ETF, not a synthetic product). There’s no oracle that connects a redemption event to an address balance, no obligation for any custodian to show which withdrawals match which headline.
ETF redemptions can take days to settle. Some redemptions unwind shares for fiat, not coins. Some move coins between custodians without ever passing them through a settlement the chain can see. There are products that use swaps rather than physical coin at all, and there is no industry-wide disclosure point that tells you which ETH left real addresses and which remained parked. Most of the process is matched off-chain by intermediaries. The best you can do is a set of partial inferences from block explorers and an incomplete set of labeled wallets.
You cannot prove from ETF outflows that coins left Ethereum, were sold, or even moved at all, unless you watch the chain. The only facts you can check are the ones the chain records. Every big ETH movement has a visible transaction, with origin and destination, and any talk of “market impact” is fantasy unless you can tie it to a real outflow, not just a fiat redemption in a headline.
If ETF flows were real, they would leave a trail. This week’s on-chain trail reads blank.
Price Moves Are Not Coin Moves – and Not All Hedging Shows Up
When $1.11 billion leaves ETFs in a week where volatility spikes, the social media cycle starts: large funds are dumping, risk is high, ETH is vulnerable. The charts move. That does not mean coins moved. Most of the time, price volatility reflects leveraged positioning, secondary market trading, and hedging—none of which require an actual on-chain transaction.
Trading an ETF share is not moving a coin. A redemption might not be, either. You might see a sell-off in paper, not in custody. You might see synthetic redemptions—they net in fiat, not crypto. If ETF outflows mattered for coins, the coin record would show it. This week, no whales moved, at least not in a way that anyone could measure and publish.
The idea that “ETF outflow = bearish for ETH” is speculation until it matches up with on-chain flows. As of now, nothing confirms that story.
If I Were Wrong, the Chain Would Show—Here’s What I’d Expect Instead
If I am wrong—that is, if ETF outflows meant actual Ethereum was leaving the network in meaningful volume—here is what the public data should look like:
- Significant uptick in net ETH outflows from custodial wallets during the redemption period, with one or more transactions traceable to ETF custodians.
- Surge in transfer volumes aligning in time and quantity with ETF redemption disclosures.
- An identifiable pool of receiving wallets (probably exchange-linked or treasuries) taking the inflow within that window.
- Net movement on Etherscan that at minimum echoes the volume in the ETF release.
I am not guessing what these would look like. This is the usual footprint when whales rotate or distribute—large, batched transactions, consolidated in a small number of hops, with on-chain data matching the headlines at scale. The absence of these traces is the point: there is no proof of mass outflow, only reports of ETF share redemptions.
If you claim that funds really sold ETH, where are the coins?
This Week’s Other Numbers: Noise Dressed as Signal
Bridge hacks, MEV bots, ETF outflows, whale alerts—most weeks, these get stacked together. The biggest exploit in the headlines: a DeFi bridge bug that created $46 billion in fake BTC tokens using a few bits of real bitcoin. The reported preliminary loss? 9.97 BTC, with 15 BTC later recovered. That’s a trivial number relative to the outlandish “2,000x supply minted” headline, and it has little to do with Ethereum, or any ETF, or real coin flows.
Anyone reading headlines this week would see two numbers side by side: billions lost in ETFs, billions printed by an attacker. In both cases, the number that moves markets is disconnected from the movement you can actually verify.
The gap between surface noise (the number in the headline) and the thing you can prove (the number in public settlement) is the story almost every week.
What a Real Whale Flow Would Tell You
A real whale alert—one with a stance, one with a number—would be explicit:
- 5,000 ETH moves from cold storage to exchange.
- 10,000 ETH is swept from one multi-sig to another.
- On-chain positions rotate out of one basket and into stETH or similar.
It would come with a hash. It would be timestamped and visible in public, Etherscan-verifiable. There would be arguments about whether it meant distribution or just rebalancing, but nobody could fake the fact of the move.
You can ignore most news, but you cannot ignore an on-chain footprint.
This week, the whale record is blank. When whales actually move, it will not be an ETF outflow number—it will be a real transaction, visible to anyone who checks. That is what matters. If there is no footprint, there is no movement.
The Strongest Objection: ETF Activity Will Show Up After a Lag
Here’s the core objection: ETF redemptions work on a delay. You could argue all week that coins haven’t moved yet, but custodians may still be unwinding their books. The on-chain flow would show up in the next period, not in the same news cycle.
That argument is not wrong. Real outflows can lag headlines by days, sometimes even longer, depending on settlement schedules, batch processing, and fund-level mechanics. Maybe we just have not seen the evidence yet.
But here’s the counter: If the ETF headline is “$1.11 billion out,” the meaningful movement must eventually show up as real coin movement, and the scale cannot be hidden. If it has not appeared after several days—no large jumps, no multi-million ETH transactions, no custodial wallet emptying—then the most likely story is that the outflows were either not coin-backed, not settled in ETH, or were matched internally.
More importantly, markets move on the story the headlines tell. If the price has already collapsed and critical outflows have not landed on the chain, the narrative outpaces the chain by days. If you move your coins because the news told you to, you are front-running a story whose reality you cannot check.
In other words, even if some ETF activity appears later, its direct causal force is weaker than the narrative implies.
The Mechanism – What Actually Happens When an ETF Redeems
Disentangling news from chain in ETF flows requires understanding how redemptions operate. Step by step:
- An investor sells ETF shares.
- The fund may redeem those shares directly—if allowed by structure.
- The redemption may be settled in cash (fiat) or in-kind (ETH).
- If cash, the fund can net it out using reserves, or by offsetting with inflows, or eventually by selling actual ETH. But that sale might be handled with OTC swaps, partner market makers, or even paper contracts—not always on-chain.
- If the redemption is settled in ETH, the coins move out. This is the scenario that would leave a footprint.
- The recipient’s wallet—if public—records an inflow large enough to match the redemption.
Only the last two steps require on-chain movement. In most cases, and certainly this week, there is no sign that step was actually taken.
Some redemptions can net out without real coins ever leaving—synthetic structures, paper-only products, swaps and back-to-back trades, all can give the impression of movement in the ETF while custody remains static.
If you want to know whether redemptions matter, look for the actual outgoing transfers, not just the reported numbers.
Headlines Move Price. Blockchains Move Coin.
This is the reframe I want to land: a price move is not a coin move. Billions of dollars can exit paper goods without moving a single private key. The blockchain record is the only one that cannot be rewritten or spun.
Every ETF outflow this week is noise unless it reconciles to real-world coin departure. The only movement that matters long-term is the one you can cross-reference—on-chain, in public, no headlines needed. Everything else is some version of theater.
The Fear & Greed Index Misses the Point
Fear & Greed is at 71—greed. Plenty of traders treat this as proof of sentiment, or momentum, or future risk. It’s a reaction to price. But price and coin movement are not the same currency. ETFs did not see authentic selling pressure in the coin record. Fear & Greed tells you about trader posture, not custody.
If you’re acting on the index alone, without checking where the coins sit, you are reacting to a mood.
What Matters This Week—And What Doesn’t
There is nothing urgent to do unless you are bridge admin or directly involved in a redemptions desk. The on-chain record is static, not panicked. If you care about the record, check on-chain flows yourself.
I use Siade Whales because I do not trust headlines to show me what is happening to my stack. The tool reads the chain, not the press release.
https://siadewhales.com
The only thing I will move on is this: Whatever the ETF headlines say next week, verify it on-chain before believing it. Price is what the crowd says; movement is what the chain shows. Everything else is noise.